COMMENTARY AND OPINION
The Reserve Bank has lifted the cash rate to 4.60 per cent after warning that several of the upside inflation risks it identified in August 2026 are now materialising.
Global energy prices are higher than the RBA had assumed, technology-related goods prices are rising quickly, and domestic capacity pressures remain.
Monetary policy is just the RBA’s fancy word for the framework through which the RBA influences interest rates, credit conditions and demand across the economy. Right now, they are tightening policy which means they are lifting rates to slow down spending and lower demand for goods and services.
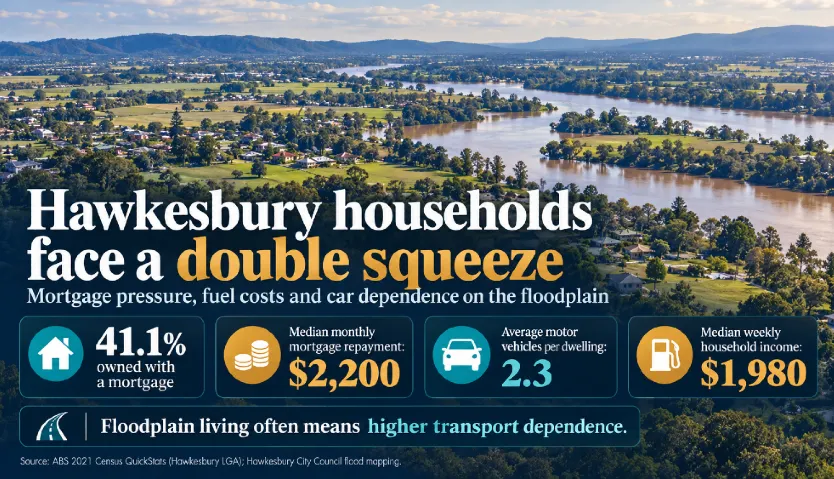
That tightening places additional pressure on households with mortgages and businesses with debt. It also inevitably becomes part of the political debate over cost of living, even though responsibility for inflation is spread across domestic demand, global supply shocks and other economic forces.
But the RBA's decision to lower demand also exposes a structural weakness in the way it manages inflation. RBA still relies heavily on a tool designed to suppress demand even when part of the price shock comes from overseas supply.
The idea here is that if consumers are charged more on interest then they will have less money to spend which correspondingly means less buying, less travel, less overall demand, and ultimately slower price growth and therefore lower inflation.
This highlights a classic dilemma in monetary policy: interest rates are a blunt policy instrument. When inflation is driven by supply-side shocks such as the recent global shipping bottlenecks, or wars disrupting energy supplies, raising interest rates cannot fix the underlying supply shortage. It cannot produce more oil, nor can it open up a shipping route or repair an international supply chain.
An interest-rate rise can reduce your spending but it cannot produce another barrel of oil, reopen a shipping route or repair an international supply chain
In this article, I explore whether Australia can broaden its policy toolkit without weakening the RBA’s mandate or abandoning monetary tightening.
This is not an argument about which government caused inflation, nor is it an argument against the independence of the Reserve Bank. Rather, it asks whether Australia’s existing policy framework gives governments, the RBA and other institutions enough complementary tools when part of the inflation problem originates from external supply shocks.
My proposal: Equity based monetary policy
I propose that all sides of politics, policymakers, economists, regulators and the banking sector examine what I call equity-based monetary policy.
During exceptional inflation episodes, instead of delivering the entire household tightening effect through higher interest costs, part of the adjustment could potentially occur through compulsory mortgage principal reduction or a locked mortgage-linked savings mechanism.
The principle is simple. If a household must temporarily lose spending power to help cool demand, some of that sacrifice could remain on the household balance sheet as lower debt or locked savings, rather than all of it becoming an additional interest expense.
For mortgage holders, equity-based monetary tightening would work like compulsory saving. It would still reduce their ability to spend and therefore restrain demand, but instead of increasing the household’s interest burden, part of the payment would build equity or locked savings.
Higher interest rates strengthen bank income, but they are not the only way to improve financial resilience. Reducing mortgage principal also strengthens the system by lowering household leverage and reducing banks’ credit exposure. If the objective of monetary tightening is to remove spending power from the economy, part of that adjustment could potentially be achieved through compulsory principal reduction rather than entirely through additional interest expense.
There are substantial questions that would need to be resolved, including banking contracts, renters, investors, people without mortgages, liquidity, prudential regulation and the institutional independence of the RBA. And these are reasons to investigate the idea further, rather than reasons not to examine it.
What about the alternatives being discussed online?
Recent Australian finance discussions have raised two other ideas: temporarily increasing compulsory superannuation contributions, or using a higher GST to suppress spending. Both contain a valid economic intuition: inflation can be reduced if current consumption is restrained. But neither is a clean substitute for monetary policy, and both have important weaknesses.
The strongest lesson from these alternatives is that the cash-flow burden of fighting inflation could potentially be shared more fairly across Australian households, while recognising that cash flow is only one of the channels through which monetary policy works.
What does equity-based monetary policy do to a household?
Instead of applying every additional increment of monetary tightening through higher mortgage interest, imagine that part of the adjustment is directed into compulsory mortgage principal reduction.
This amount leaves the household's current spending budget immediately, but remains on the household balance sheet as lower mortgage debt.
Watch the effect build over 12 months
The first interest saving is small because only one equity payment has been made. Each additional payment lowers the mortgage balance again, so the interest saving gradually accumulates.
| Month | Equity payment | Total extra principal | Monthly interest avoided |
|---|
Why doesn't the interest saving immediately undo the anti-inflation effect?
In the first month, the household gives up $156.25 of current spending power. The resulting interest saving in the next month is only $0.81.
Most of the adjustment therefore remains embedded in the household balance sheet as lower debt rather than immediately returning to consumption.
As the process continues, however, the household progressively owes less principal and therefore pays less interest. The short-run demand restraint occurs immediately, while the household balance-sheet benefit accumulates gradually.
Illustrative model only. The equity payment is calculated as the selected annual equity-policy percentage of the outstanding mortgage balance, divided by 12. The projection isolates the additional equity-policy effect and does not reproduce a complete mortgage amortisation schedule.
Sources and methodology.
Reserve Bank of Australia, Statement on Monetary Policy, August 2026, especially Financial Conditions and Outlook (Graphs 1.1, 1.11, 3.3, 3.6, 3.7, 3.8 and 3.9; Table 3.1). RBA Monetary Policy Decision, 29 September 2026. The scenario graphics are from my monetary-policy transmission dashboard. Scenario parameters are illustrative and are not official RBA forecasts.
Rosh D’Souza is a Hawkesbury resident and Hawkesbury Gazette contributor. The views expressed are his own.